How do you earn a return on trade spend when retailers demand more and shoppers buy on promotion?
Unlock annualised EBIT equal to 1.75–2.5% of revenue within 90 days
You build brands and ranges shoppers choose, and you invest to keep them on the shelf and in front of the shopper. Then last year’s promotions go back into the plan because the budget depends on them, rebates are paid on turnover whatever the account achieved, and every line is matched as if shoppers compared it. Margin seldom goes in one decision. It drains away through eight familiar habits: value that is never defined, prices built up from cost, a commodity mindset, discounts given to win or keep business, procurement out-negotiating the sales team, increases that never reach the invoice, price structures too tangled to manage, and leaders pulling in different directions.
Eight disciplines win it back: list prices, customer discount levels, overrides, rebates, channel pricing, price optimisation, volume and mix. You know your brands, your shoppers and your accounts better than anyone. We bring 30 years of real-world pricing experience, including our work with consumer goods suppliers and retailers, and practical, step-by-step techniques that improve revenue, margins and profitability.
FMCG and retail clients include Arnott’s, Super Retail Group and David Jones. 160+ clients since 2007 in Australia, New Zealand, Asia, India, the US and the UK.
Three pressures that squeeze FMCG and retail margins
None of them is new. What has changed is that they now arrive together, and each one is a pricing decision as much as a market condition.
Retailers and buying groups that demand more funding
- Category buyers negotiate trade terms, rebates and promotional funding as one package, account by account.
- Rebates are paid on turnover, and concessions are given without a range or growth commitment in return.
Competitors who keep promoting
- A competitor’s promotion triggers a match across the range, including lines shoppers never compare.
- Each brand, account or buying group runs its own offers, and they compete for the same shopper.
Shoppers who have learned to wait
- More of the year’s sales are made on promotion, and event weeks pull sales from the weeks around them.
- The promoted price becomes the price shoppers expect, and full price stops meaning anything.
Eight ways margin erodes, and eight ways to win it back
Our 16 margin techniques set out where margin leaks and where it can be recovered. In FMCG and retail, each one takes a familiar form.
Eight ways margin erodes
Undefined value drivers
Teams cannot say what the brand, pack or range is worth to the shopper or the account, so they lead with funding.
Cost-plus pricing
Prices set from cost plus a target margin, or by following the recommended retail price down.
Commodity mindset
“Shoppers only buy on promotion” becomes the plan, and price matching becomes the strategy.
Discounting to win or keep business
Promotions and markdowns repeated because last year’s budget was built on them.
Out-negotiated by procurement
Category buyers negotiate the whole package against account managers without the full economics.
Price increases that do not stick
Cost price increases planned late and conceded in the room, and price changes held until the next window.
Tangled price structures
Trade terms, rebates, funding and offers layered across accounts, brands and channels with no shared rules.
Management misalignment
Sales chases volume, marketing chases share, finance chases margin, and the price falls between them.
Eight ways to win it back
List prices
Pack and price architecture with clear price points and good, better and best ladders.
Customer discount levels
Published entitlements by channel and account tier, so a smaller account never pays less than a major partner.
Overrides and tactical discounts
Approval rules for promotions, markdowns and discretionary discounts, reported each month.
Rebates
Rebates tied to growth, range or mix achieved, with a term and a review date.
Channel pricing
Pricing consistent across grocery, foodservice, online and store channels, and across brands.
Price optimisation
Key lines priced to the market, the rest of the range priced to its value, and cost price increases passed through on a schedule.
Volume management
Promotional return measured after pull-forward and funding, so volume events are tested against margin.
Mix management
Range and pack decisions that move sales towards higher-margin products and formats.
A 1% price rise on $100m of revenue adds $1m to EBIT, with the same volume and the same cost base.
From and towards: nine elements that decide margin in FMCG and retail
The Pricing Periodic Table sets out 61 elements of pricing capability in nine domains, across Value, People and Structures. In FMCG and retail, our work most often starts with these nine.
Value
What the customer gains and how you charge for it
Segment and channel strategy
Published price entitlements by channel and tier.
Rebate and incentive design
Each rebate with a term, a review date and a hurdle.
Competitive response rules
Match only on key value items, with written evidence.
People
Who decides price and how well they are equipped
Key-account negotiation plans
Full account economics after trade spend, before each negotiation.
Concession planning
Each concession bought with a commitment to more of the range.
Commercial numeracy
Teams who can work out what an offer does to margin dollars.
Structures
The analysis, price architecture and systems pricing runs on
Price position and key value items
An agreed list of the lines shoppers compare.
Price modelling
Each promotion and cost increase modelled before it enters the plan.
Price realisation KPIs
A margin walk: price, cost, mix and new and lost lines.
From and towards
How we make it happen
Four stages take a supplier or retailer from the size of the opportunity to prices and promotions that earn their place.
Diagnose
We review trade spend, promotional and markdown return, price position on the lines shoppers compare, consistency across brands and channels, and how trading terms work in practice, then size the opportunity in dollars.
Optimise
We set a price architecture that competes on the lines shoppers compare and earns margin on the rest, price ladders by category, a promotional calendar built on contribution and a plan for the next cost price increase.
Embed
Buyers, planners and account managers get approval rules for promotions and markdowns, trade terms with conditions attached and training in pricing arithmetic and promotional evaluation.
Review
We track promotional return, markdown performance and price realisation each month against an agreed baseline, through the next sale season and the next trading terms negotiation.
FMCG and retail client results
Each result is labelled. Realised: measured after implementation. Identified: opportunity sized in the diagnostic, before implementation. Figures in Australian dollars.
Low-return promotional activity cut by more than 30%, and about A$200k of annual channel fines eliminated.
Read the case studyRealisedA national price list architecture and discount matrix, with a further A$6m–9m of margin opportunity identified.
Read the case studyRealisedPricing and markdown rules aligned across four retail brands.
Read the case studyIdentifiedSKU resets, targeted promotions and clearer price ladders across stores and online.
Read the case studyPrice optimisation programs return between 5 and 10 times their cost in year 1.
Four questions FMCG and retail executives ask
Can we cut promotional spend without losing volume?
In many ranges a share of events returns little once pull-forward and funding are counted. Those can be cut or redesigned with little effect on annual volume. Arnott’s cut low-return promotional activity by more than 30% and recovered over A$5m of EBIT within 12 months.
Can we hold a premium position when competitors keep discounting?
Yes, when you are clear about where you compete. A small set of lines shapes how shoppers judge price, and those are matched. On the rest, range, service, exclusivity and how value is presented carry more weight than a deeper discount.
Can we get a cost price increase through with the major retailers?
It is more likely when planned before the negotiation: which packs hold the price point, which carry the rise, what the trade terms buy in return, and the evidence for the retailer’s category team.
How do we keep prices consistent across our brands and channels?
One set of pricing rules, approval limits and markdown reporting across the group. Super Retail Group aligned pricing across four brands and cut ad hoc discounting by up to 50%.
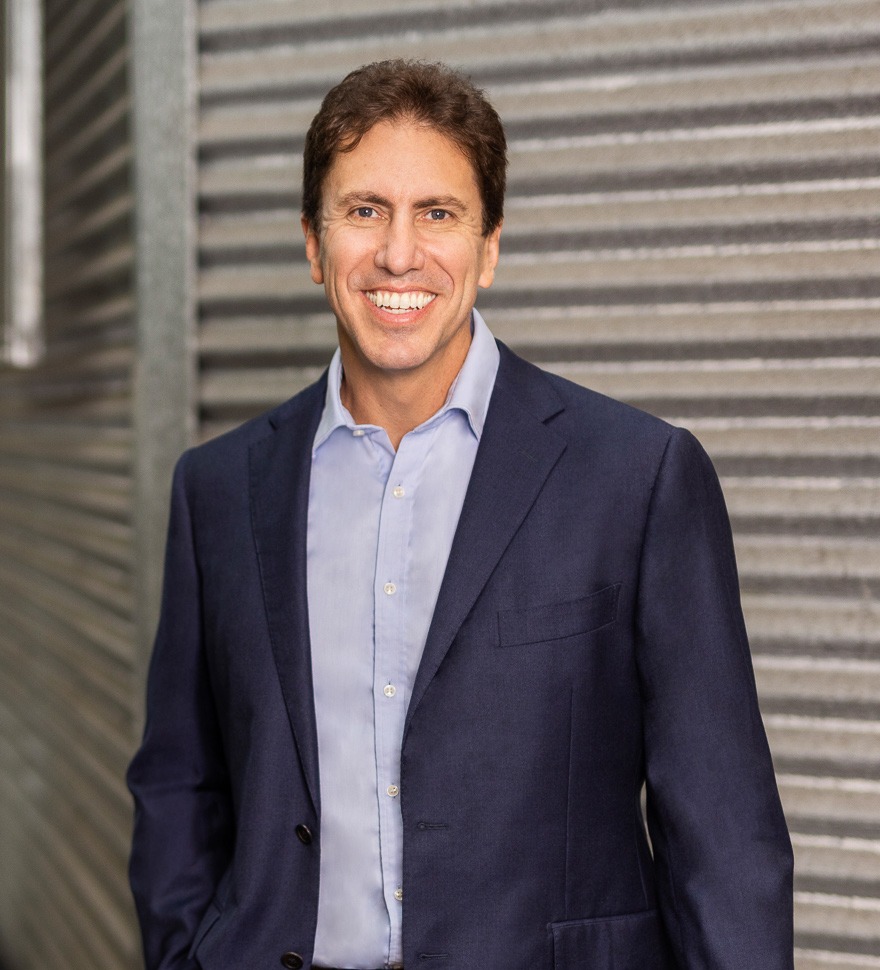
Ron Wood, Founder and Managing Director
Ron began his career as a pricing and commercial manager in industry, including building materials, FMCG and capital equipment. Since founding Pricing Insight in 2007 he has worked with more than 160 clients in Australia, New Zealand, Asia, India, the US and the UK, among them Arnott’s, Super Retail Group and David Jones.
He leads each engagement with a senior associate, working alongside your buyers, planners, account managers and store teams. Your team knows the brands and the shoppers. We bring the method, the evidence and the discipline that make new prices hold.
Discover your margin improvement opportunity
Talk to Ron Wood about the pressures on your prices: the funding request from the next account review, the competitor’s promotion, the event repeated because the budget depends on it. In a 30-minute call he will work through where margin is made and lost in your business, and the first steps to capture more of it. Call +61 410 534 099 or email info@pricinginsight.com.au.
Discuss your margin opportunities