Industrial equipment companies protect margin by pricing the whole life of the machine, not only the initial sale. That means pricing the configuration rather than the base machine, running large deals through a deal desk, giving dealers one clear price logic, pricing parts by availability and competition, packaging service around uptime, placing new, used, rental and subscription offers on one price ladder, writing cost, tariff and currency clauses into quotes, and tracking price realisation every month. These eight decisions apply to global manufacturers such as Caterpillar, Amada, DMG Mori, Sumitomo Heavy Industries and XCMG, and to Australian importers and distributors, because each sells a long-lived asset into a market where list price is rarely the price paid.
Key takeaways
- Price realisation, not list price, decides equipment margins: Caterpillar's 2025 sales grew 4% on volume while price realisation reduced sales by US$817 million.
- Discount discipline shows up in the numbers: DMG Mori's average machine order price rose 12% in 2025, helped by a richer mix and lower discount rates.
- Parts and service carry a larger share of profit than new machines, so they need their own price logic rather than a cost-plus markup.
- Tariffs, currency and input costs move faster than equipment price lists; quotes need clauses that pass these movements through.
- New, used, rental and subscription options compete for the same customer and should be priced as one ladder.
Why does pricing industrial equipment need its own approach?
Why is price realisation the number that matters?
Equipment makers report sales growth, but the margin story sits in price realisation: the difference between the price planned and the price achieved after discounts, dealer support and deal terms. Caterpillar's 2025 sales and revenues rose 4% to US$67.6 billion, driven by US$3.4 billion of higher volume, partly offset by US$0.8 billion of unfavourable price realisation (Caterpillar 4Q25 results). In its annual report, Caterpillar said operating profit fell 15% to US$11.2 billion, reflecting US$2.1 billion of unfavourable manufacturing costs, largely higher tariffs, and US$817 million of unfavourable price realisation (Caterpillar 2025 annual report).
The split by segment tells the same story. Construction Industries sales fell 2%, mainly because of US$1.1 billion of unfavourable price realisation, while Power & Energy grew 12% with US$592 million of favourable price realisation (Caterpillar 2025 annual report). The same company, in the same year, saw price help in one market and hurt in another. Price realisation needs to be managed segment by segment.
Why is price competition intensifying?
Global capacity is a major factor. China's construction machinery exports reached US$60.2 billion in 2025, up 13.8%, and excavator exports rose 16.1% to 116,739 units (Everbright Securities via Futu). One industry analysis said whole-machine prices in China remained depressed, and attributed the price competition to capacity built for the 2021 peak exceeding current demand (China construction machinery report).
XCMG illustrates the shift. Its overseas revenue rose 16.6% to RMB 48.6 billion in 2025, or 48.2% of total revenue, up 3.4 percentage points in a year (XCMG via Morningstar). For Australian buyers and distributors, this means more choice at more price points, and more pressure on established brands to show why their machines are worth more.
Japanese manufacturers have been open about the cost of slow pricing. Amada said that delays in passing on price increases, together with rising material and labour costs, caused it to fall short of the operating margin and ROE targets in its previous medium-term plan (Amada). Sumitomo Heavy Industries lists "implement price pass-through measures" as a response strategy for its Mechatronics business, and "price revisions and consolidation of models to improve profitability" for its gear business (Sumitomo Heavy Industries Integrated Report 2025).
Why does the life of the machine matter as much as the sale?
A machine sold today creates demand for parts, service, upgrades and eventually a replacement or trade-in. Caterpillar has a target of doubling services revenues to US$28 billion by 2026 from the 2016 level (Zacks), and one broker report put its 2025 Machinery, Power & Energy services revenue at about US$24 billion, around 36% of sales, on an installed base of more than four million products (PSG).
DMG Mori's Japanese parent reported that maintenance, repair and overhaul, spare parts and engineering made up 24% of consolidated orders in 2025 (DMG Mori Co., Ltd.). At DMG Mori AG, the Industrial Services segment made up 47% of 2025 order intake (DMG Mori AG). Amada's after-sales revenue grew 5.3% in the year to March 2025 while machinery revenue fell 3.4% (Amada via MarketScreener).
The economics favour the aftermarket. McKinsey found average EBIT margins of 25% for aftermarket services against 10% for new equipment across 30 industries (McKinsey), and BCG reports average gross margins of 50% on spare parts and consumables (BCG). A discount on the machine may be recovered over its life, but only if parts and service are priced with the same care.
How are currency and tariffs changing equipment prices?
Most industrial equipment sold in Australia is imported, so the Australian dollar moves landed cost directly. In September 2025, the ABS import price index for general industrial machinery and equipment fell 2.6%, which the ABS attributed to the Australian dollar's appreciation against the US dollar (ABS). A stronger dollar lowers cost, but customers expect the saving to show in price; a weaker dollar lifts cost, and the supplier must recover it quickly.
Tariffs added another layer. Caterpillar reported net incremental tariff costs of US$1.7 billion in 2025 (Fortune). DMG Mori said the effect of US tariffs in the first quarter of 2025 was minimal and that it responded through surcharges (DMG Mori Co., Ltd. Q1). A surcharge mechanism agreed in advance is far easier to apply than a price increase negotiated deal by deal.
What do Australian distributors show about the market?
Australian equipment suppliers compete on range, stock, service and speed as well as price. Hare & Forbes Machineryhouse has supplied workshop and engineering equipment since 1930, carries more than 30 agencies sourced from countries including Taiwan, China, Germany, Japan and the USA, and states that its founding principle is an extensive range "at the best possible price" (Hare & Forbes). Its services include machine testing, installation, training, finance, spare parts, warranty and onsite repairs (Hare & Forbes Modern Slavery Statement).
Power Machinery, the Australian distributor for Ermaksan, offers nationwide delivery, installation and operator training (Power Machinery), and its in-house technicians service most industrial metal fabrication machinery, not only the machines it sells (Power Machinery service). Ernest Fleming Machinery & Equipment supplies new and second-hand processing and packaging machinery, as well as complete process lines and plants (Ernest Fleming). M&E Equipment Traders buys redundant plants and processing lines, and says customers can save up to 80% compared with the price of new equipment (M&E Equipment Traders).
These businesses show that the customer's choice is rarely "this machine at this price". It is new or used, buy or hire, with or without installation, training and service, delivered now or in six months. Each option needs a price that makes sense next to the others.
What are the eight pricing decisions for industrial equipment?
The eight decisions follow the life of the machine: the sale, the years of use, and the protection of price against cost and currency.
Part 1: Selling the machine
Decision 1: Price the configuration, not the base machine
Industrial equipment is rarely sold as a base model. Options, attachments, controllers, automation and tooling can change the value of a machine to the customer more than the base specification does. DMG Mori's average machine order price rose 12% to JPY 79.6 million in 2025, which the company attributed to higher orders of MX and large machines and lower discount rates (DMG Mori Co., Ltd.). Amada stated an aim to improve selling prices in sheet metal by increasing the share of new products (Amada via MarketScreener). Power Machinery offers the same Ermaksan press brake with a choice of controllers (Power Machinery), a small example of how configuration shapes price.
What to do: Build a configuration price book with a target margin for each option and attachment, not only for the base machine. Price options on the value they create, such as cycle time, automation or reduced setup, rather than as a percentage uplift. Check the margin of every configured quote before it goes out, and stop sales teams giving options away to close the machine sale.
Decision 2: Put large deals through a deal desk with clear discount authority
Large equipment deals carry large discounts, and discounts given under pressure become the next customer's starting point. Caterpillar's unfavourable price realisation in Construction Industries shows how quickly deal terms can erode a list increase (Caterpillar 2025 annual report). DMG Mori's result shows the opposite: lower discount rates contributed to a higher average order price (DMG Mori Co., Ltd.).
What to do: Set discount bands by machine family, customer segment and deal size, with named approvers for each band. Send deals above a threshold to a deal desk that checks margin, configuration, trade-in value, finance terms and service attachment together. Record every approved exception with its reason and margin effect, and review win rates and realised price each month. Competitive deals should be decided on evidence of the competing offer, not on the sales team's estimate.
Decision 3: Give dealers and distributors one clear price logic
Many manufacturers sell through independent dealers who set their own resale prices. Caterpillar states that the terms of sale, including price, under which each Cat dealer sells are set independently by each dealer (Caterpillar), and its network of around 160 independent dealers serves 197 countries (Caterpillar). Sumitomo Heavy Industries names dealer enhancement and expanded sales channels, including alliances, as strategies for its construction machinery (Sumitomo Heavy Industries). In Australia, distributors such as Hare & Forbes carry agencies from many manufacturers at once (Hare & Forbes).
What to do: Define what each channel partner is paid for: stocking, demonstration, installation, service, finance or territory coverage. Tie dealer margin and support to those roles, not only to volume. Make sure dealer support for one large deal does not reset the price in the territory. For distributors carrying several brands, set a clear price position for each brand and model family, so the range offers a good, better and best choice rather than overlapping prices.

Part 2: Earning across the life of the machine
Decision 4: Price parts by availability and competition, not by cost plus a markup
Parts are often priced with a single markup on cost, which overprices fast-moving parts that face competition and underprices slow, specialist parts that only the manufacturer can supply quickly. Parts margins are high on average, with BCG reporting average gross margins of 50% on spare parts and consumables (BCG), but the average hides wide variation by part. Caterpillar's parts portal offers online ordering backed by local dealer support (Caterpillar), which shows how parts buyers increasingly compare prices online.
What to do: Segment the parts range by competitive exposure (genuine-only, competing with will-fit parts, or commodity), by demand (fast, medium and slow) and by criticality to uptime. Set price rules for each segment: market-referenced prices for exposed fast movers, value-based prices for critical and proprietary parts, and minimum prices for slow movers that carry inventory cost. Review parts prices at least twice a year, and check them against currency movements.
Decision 5: Package service around uptime and outcomes
Customers buy equipment to produce output, so the cost of downtime often exceeds the cost of the service that prevents it. Amada connects machines through its V-factory system, which it uses for services that support uninterrupted operation and for operational analysis reports, and was targeting 9,000 connected machines (Amada via MarketScreener). Sumitomo Heavy Industries plans to expand high value-added service businesses using digital tools, and to strengthen after-sales service to generate stable cash (Sumitomo Heavy Industries Integrated Report 2025). Amada's Medium-term Business Plan 2030 describes a shift from a product-led model towards combining products with services, including AI and operational monitoring (Amada).
What to do: Replace a menu of hourly rates with three or four service tiers, such as basic inspection, planned maintenance, and uptime-assured service with response-time commitments and remote monitoring. Price each tier on the value of avoided downtime and longer machine life, with clear rules on what is included. Attach service at the point of machine sale, when the customer is most receptive, and track service attachment rate as a sales measure.
Decision 6: Put new, used, rental and subscription offers on one price ladder
Customers can meet the same need by buying new, buying used, hiring or subscribing. M&E Equipment Traders says used equipment can save up to 80% on the new price and can be delivered promptly without lead-time delay (M&E Equipment Traders; M&E about us). Ernest Fleming lists new, used and hire machinery on the same marketplace (Machines4U). DMG Mori's PAYZR subscription for its M1 machining centre combines a monthly fee of €599 with €5.99 per spindle hour on a 36-month term, and the monthly fee includes transport, commissioning, training, service, maintenance and insurance (DMG Mori).
What to do: Map every way a customer can acquire the capability and set the price of each relative to the others, using total cost over the period of use. Make sure the subscription price covers service, finance and residual value risk, and that the used price reflects condition, warranty and immediate availability. Price trade-ins on the expected resale value, not on what is needed to close the new machine deal.
Part 3: Protecting price against cost and currency
Decision 7: Write cost, tariff and currency clauses into every quote
Equipment quotes are often valid for months, and lead times can be longer. In that time, steel, components, freight, tariffs and the exchange rate can all move. Caterpillar's 2025 tariff costs (Fortune), Amada's delayed price pass-through (Amada) and DMG Mori's tariff surcharges (DMG Mori Co., Ltd. Q1) show why the response needs to be agreed before costs move. XCMG noted that exchange-rate movements weighed on its first-quarter 2026 profit (XCMG via Futu).
What to do: Set a validity period on every quote and a price adjustment clause for orders delivered beyond it. For imported equipment, link the price to an exchange rate band, with adjustment if the rate moves outside the band before order confirmation. Use a separate, visible surcharge for tariffs and extraordinary freight, with a rule for removing it when the cost falls. Review parts and service prices on the same currency trigger.
Decision 8: Track price realisation monthly and reward margin, not only volume
Caterpillar reports price realisation separately from volume and currency in every result (Caterpillar 4Q25 results), and DMG Mori reports average order price and its drivers (DMG Mori Co., Ltd.). Few mid-sized equipment businesses have the same view for their own sales team, branch or dealer.
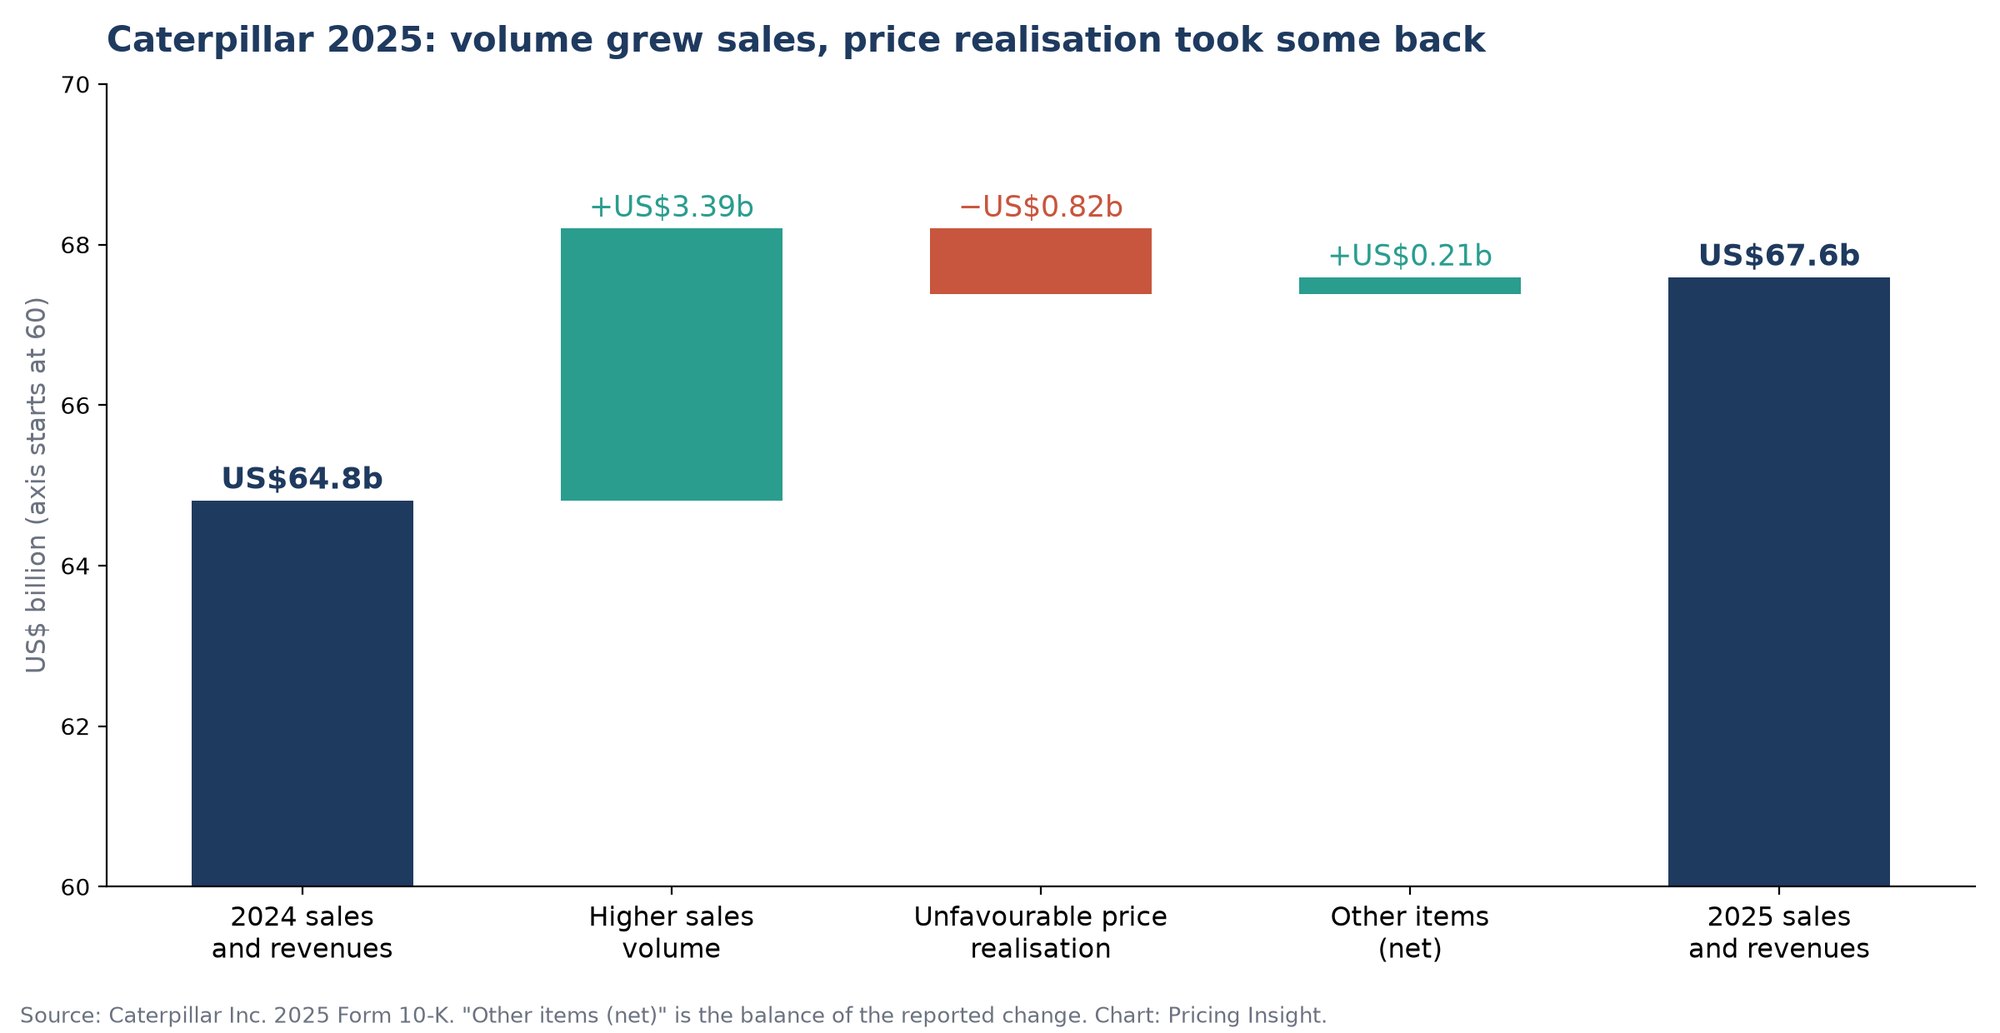
Figure 1. Caterpillar 2025 sales bridge. Source: Caterpillar Inc. 2025 Form 10-K; "other items" is the balance of the reported change.
What to do: Build a monthly bridge from last year's revenue to this year's, separating volume, price realisation, configuration mix, currency and parts and service growth. Report price realisation by machine family, segment, sales person and dealer. Pay sales teams on margin or price realisation as well as volume, and include service attachment and parts pull-through in the scorecard.
How do the decisions apply to different equipment businesses?
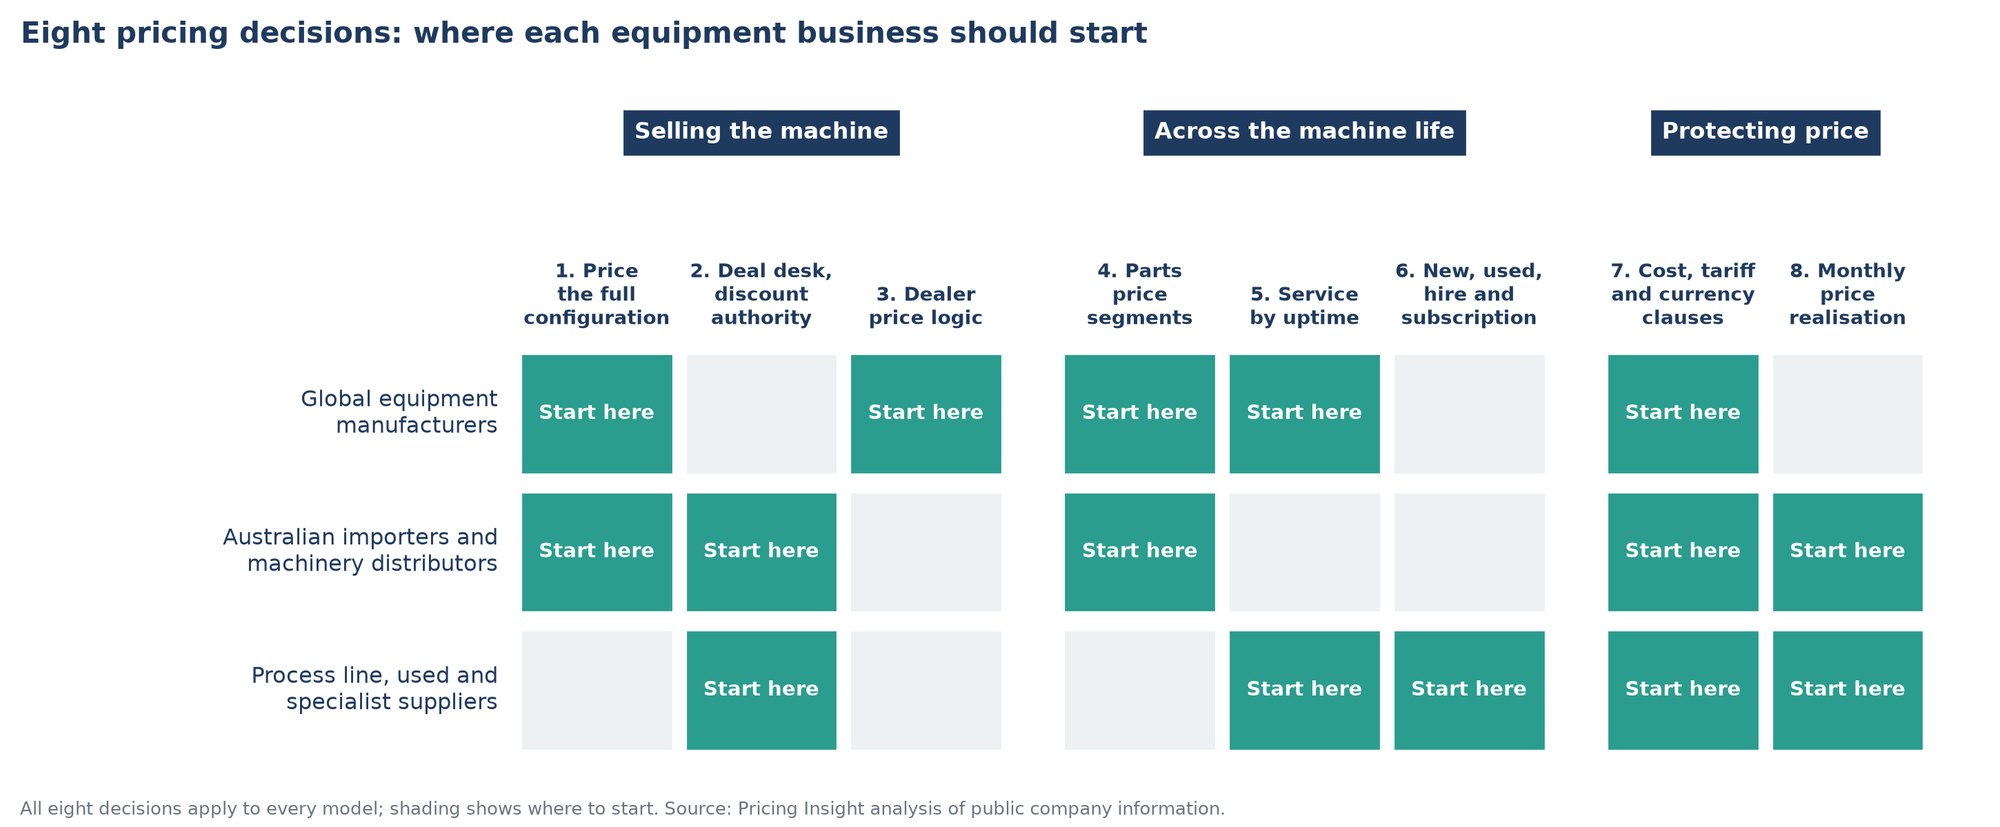
Figure 2. Where each equipment business should start. All eight decisions apply to every model.
- Global equipment manufacturers (Caterpillar, Amada, DMG Mori, Sumitomo Heavy Industries, XCMG): configuration mix, dealer price logic and the aftermarket drive margin, and global supply chains bring tariff and currency exposure. Start with decisions 1, 3, 4, 5 and 7.
- Australian importers and machinery distributors (Hare & Forbes, Power Machinery): many brands and models compete at close price points, landed cost moves with the dollar, and parts and service are a growing source of margin. Start with decisions 1, 2, 4, 7 and 8.
- Process line, used equipment and specialist suppliers (Ernest Fleming, M&E Equipment Traders): each deal is close to unique, customers compare new, used and hire, and project scope and installation need clear pricing. Start with decisions 2, 5, 6, 7 and 8.
All eight decisions apply to every model. The table shows where each typically starts.
What has Pricing Insight's equipment work shown?
Pricing Insight has worked with capital equipment, office equipment and commercial products businesses in Australia and the Asia Pacific. Published results include:
- Hyster-Yale Asia Pacific: moved from an EBIT loss of about A$100k to an A$3m EBIT gain within 12 months, through a central deal desk, discount rules, configuration profit models and electronic price and quote tools.
- Ricoh Australia: an A$8.7m–13.5m EBIT improvement opportunity identified across four business lines, with CPQ cycle time reduced by 35%.
- ITW Proline: an A$6m–12m margin opportunity identified across four business units through value tools and discount governance.
See more on our capital equipment pricing strategy page, and our companion papers on building materials pricing and packaging pricing strategy.
What should an equipment company CEO ask about pricing?
- Do we know the margin on every option and attachment, or only on the base machine?
- Who approves our largest discounts, and do we review the outcome of those deals?
- Are dealers paid for the roles they perform, or only for the volume they sell?
- Are our parts priced by competitive exposure and criticality, or by a single markup on cost?
- What share of machines leave with a service agreement, and how is service priced?
- Do our new, used, hire and subscription prices make sense next to each other?
- If the Australian dollar fell 10% tomorrow, how quickly would our prices move?
- Can we see price realisation by machine family, sales person and dealer every month?
If the answer to three or more is "no" or "not sure", the business is likely to have a material, measurable pricing opportunity.
Frequently asked questions
What is price realisation in industrial equipment?
Price realisation is the change in the price achieved for comparable equipment, after discounts, dealer support and deal terms, compared with the prior period or the planned price. It is reported separately from volume, mix and currency, so management can see whether margin moved because of pricing decisions or other factors.
How should equipment companies price spare parts?
Parts should be segmented by competitive exposure, demand frequency and criticality to uptime, with a price rule for each segment. Exposed fast-moving parts are priced against the market, while proprietary and critical parts are priced on the value of availability and avoided downtime.
How do equipment importers manage currency movements?
Most use a combination of quote validity periods, exchange rate bands with adjustment clauses, and scheduled price list reviews. The aim is to pass on currency movements in both directions, quickly and predictably, so customers trust the process and margin is protected.
Should equipment companies offer subscription or pay-per-use pricing?
Subscription and pay-per-use models suit customers who value flexibility and predictable cost. They work when the price covers service, finance and residual value risk, and when they sit on a clear ladder with outright purchase, used equipment and hire.
How long does an equipment pricing diagnostic take?
A diagnostic typically runs over several weeks, using quote, order, parts and service data, a staff capability survey and leadership interviews. Quick wins, such as discount authority and parts price corrections, start during the diagnostic, while price architecture and service tiers are rolled out over the following months.
How does Pricing Insight help equipment businesses?
Our approach follows three linked workstreams.
1. Current-state pricing diagnostic. Our 9PE pricing diagnostic and quick wins establishes how machine, option, parts and service prices are set, approved and changed by segment, channel and region; how cost and currency movements flow into realised price; and where margin is lost through discounts, dealer support, trade-ins and delayed increases. It produces a quick wins register with actions that can start immediately.
2. Value pricing framework design. We design a price architecture that is value-led rather than cost-plus: configuration price books, discount bands and approval rights, dealer margin structures, parts price segments, service tiers, and the price ladder across new, used, hire and subscription.
3. Implementation and rollout. We prioritise customers and dealers, sequence the changes, and equip sales teams with value tools, deal desk processes, negotiation packs and training. We update quoting tools and governance, and set the measures that show whether the change is working: price realisation, margin by configuration, service attachment and fewer exceptions.
About the author
Ron Wood is the Founder and Managing Director of Pricing Insight, an Australian pricing strategy consultancy he established in 2007. He has worked in pricing for around 30 years, first as a pricing and commercial manager in consumer goods, building materials and capital equipment, and since then across more than 160 pricing engagements in Australia, New Zealand, South East Asia, India, the United States and the United Kingdom. He also founded Pricing University, which has trained more than 5,000 executives.
To discuss how these decisions apply to your business, contact Ron Wood at info@pricinginsight.com.au or on +61 410 534 099, or visit Pricing Insight.
Company information in this paper is drawn from public sources, including annual and integrated reports, results releases, company websites and published analysis, as cited. Hare & Forbes, Power Machinery, Ernest Fleming and M&E Equipment Traders are privately owned and do not publish annual reports, so their information is drawn from their websites and public filings. The paper describes publicly reported facts and does not suggest any assessment of the pricing practices of the companies named. Figures are in the currency reported by each company.