Case study · Building materials · Timber and wood panels · 14 min read
Source: Pricing Insight engagement records. Company facts from Carter Holt Harvey, the New Zealand Herald and the Australian Business Register, named in the fine print. The work built a pricing structure and the business recorded margin gains; the dollar value of those gains is not disclosed.
About A$700m of timber and panels, priced from a system nobody could move. Carter Holt Harvey Wood Products sold framing timber through Woodlogic and particleboard and MDF through Pinepanels, to distributors, hardware retailers, cabinet makers and independent chains, in a market under constant price pressure and tied to the housing cycle. It had also merged two sales cultures, one selling on 15 to 20 per cent gross margins and one on 30 to 45 per cent. Ten years of permanent price overrides, keyed at customer and SKU level in SAP, meant a list price change no longer reached the invoice, and some customers paid the same price five years later while costs had risen 15 to 20 per cent. Prime timber lengths sold at the same rate per metre as mid-range lengths, surplus mid lengths built up and were written off, and prices clashed between channels, most visibly between Bunnings and Mitre 10 on a structural flooring product. Pricing Insight built a new list price architecture with correct relativities, discount entitlements set by each customer's spend, performance-based rebates for accounts spending A$1m or more under a return on rebate investment model, contract terms on order timing and load size, a stock-to-sales discount calculator that cleared surplus lengths through selected customers without pulling down market prices, and a new measure for overrides based on the revenue and gross margin of the whole account. Together they rebuilt margin at both a tactical and a strategic level.
| Client | Carter Holt Harvey Wood Products Australia: Woodlogic, the framing timber business, and Pinepanels, the particleboard and MDF business supplying cabinetry and kitchen manufacture. |
| Service | Pricing strategy, price architecture, rebate and contract design. |
| Status | Capability built. New list price architecture, customer discount entitlements, performance-based rebates and contract terms in place; the business recorded margin gains, not disclosed. |
| Scope | About A$700m of annual sales; hundreds of thousands of customer and SKU price combinations in SAP; four channels: distributors, major retailers, cabinet makers and kitchen manufacturers, and independent chains. |
| Channels | Distributors such as Gunnersen and Timbermark; retailers Bunnings, Mitre 10 and Dahlsens; cabinet makers and kitchen manufacturers; smaller independent chains. |
The brief
Bring price back under control across timber and panels, so list price changes reach the invoice, each customer pays for what it buys, and the largest customers bring more of their spend.
01Two businesses, two margin cultures and one sales force selling into four channels
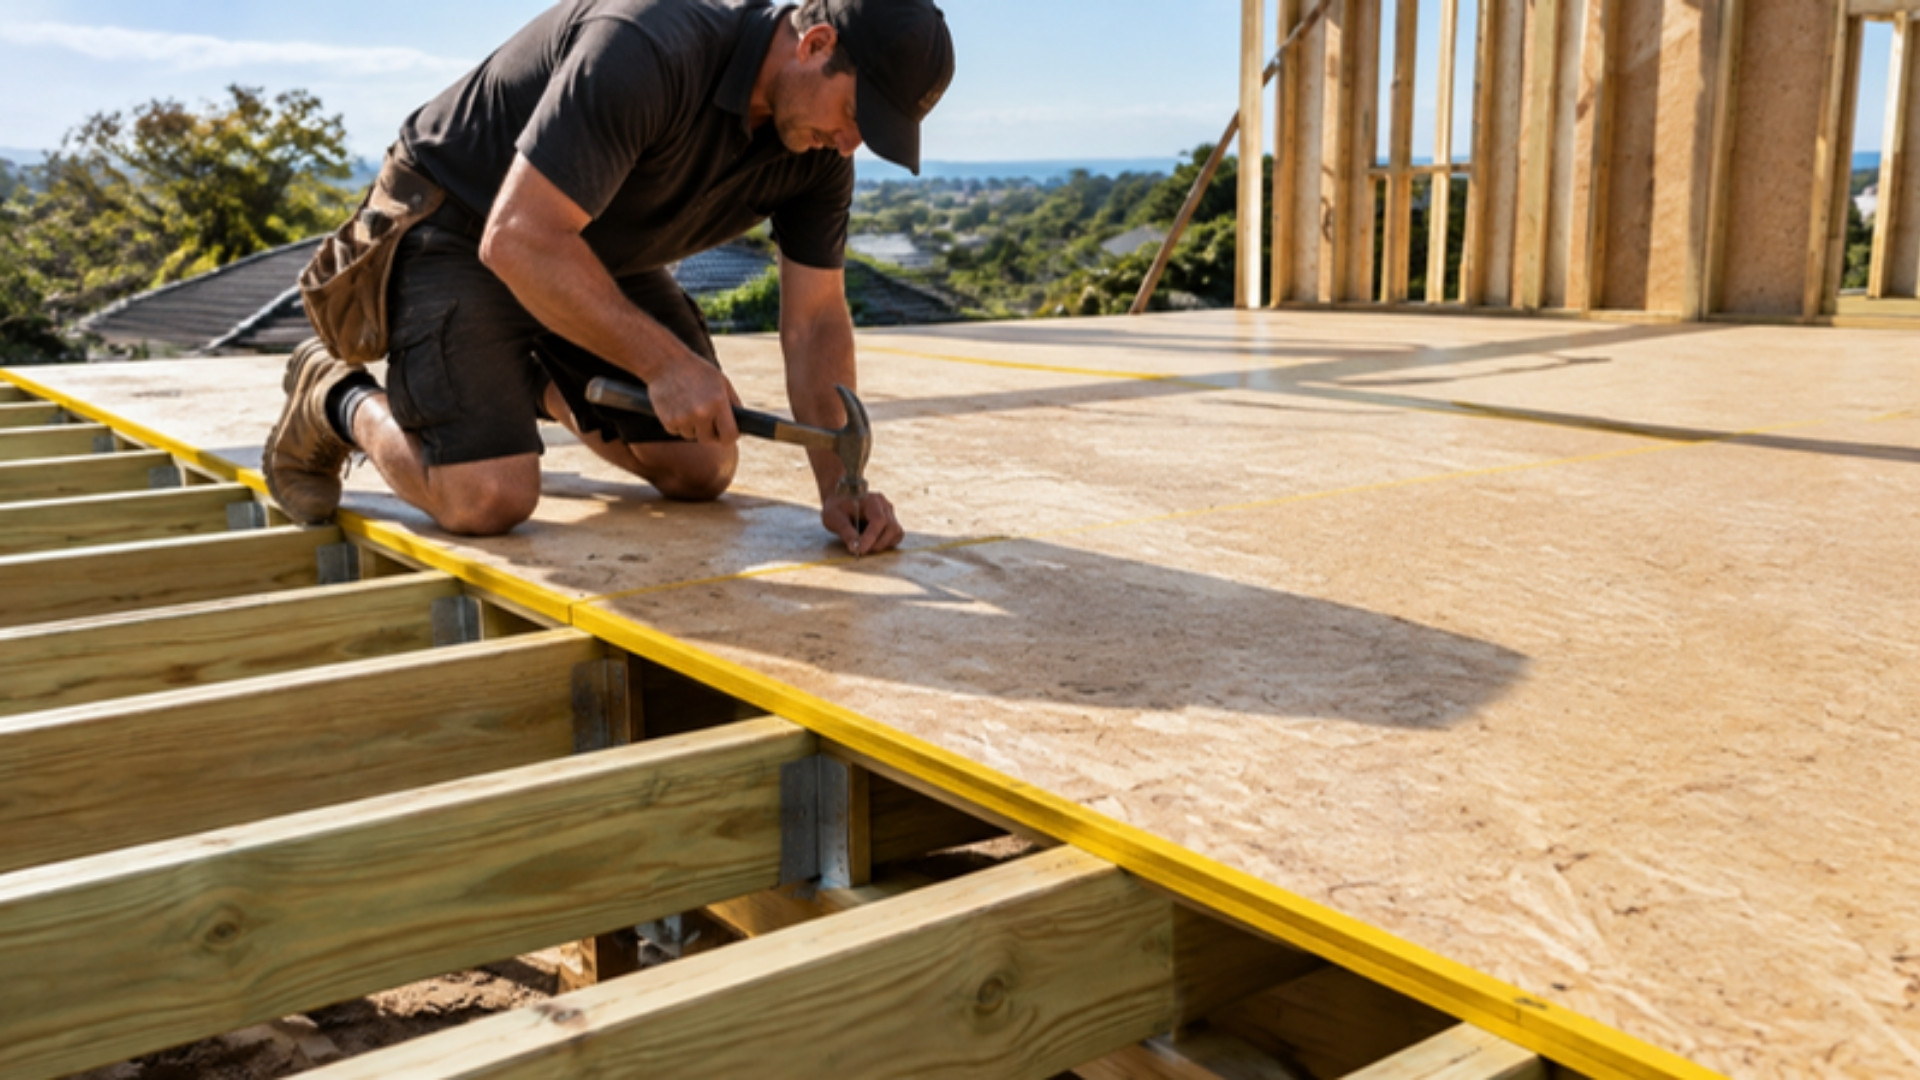
A pine processor selling the frame and the fit-out of a house. Carter Holt Harvey built its Australian wood products business largely by acquisition, including CSR's particleboard and MDF plants (New Zealand Herald). Woodlogic sold structural framing timber; Pinepanels sold particleboard and MDF, most of it used in cabinetry and kitchens. Together they sold about A$700m a year through four channels.
The market gave the business little room. It was heavily price-pressured, with many competitors chasing the same customers. It was cyclical, rising and falling with housing starts. And when starts rose, framing timber became scarce, so the price had to reflect scarcity in the upswing as well as competition in the downswing.
Two cultures had been merged into one. In stick framing timber, gross margins ran at 15 to 20 per cent and EBIT margins were often 2 to 3 per cent, so the sales team weighed every discount: with 20 per cent of gross margin to work with, there was little to give. In particleboard and panels, gross margins ran at 30 to 45 per cent, and the culture of discounting to drive volume was much more liberal.
02What the review found: prices fixed in the system, every length at one rate, and stock that ended in write-offs
Nine problems, most of them years old. The findings fall under the three pillars of the Pricing Periodic Table.
Value
Prime lengths were priced as if they were worth no more than mid lengths. A 6 metre length sold at the same rate per lineal metre as a mid-range length, although builders value it more. Standard houses are framed to 2.4 and 2.7 metre wall heights, so the 2.4 and 2.7 metre lengths, and the 5.4 and 6.0 metre lengths that cut into them, are used with little waste. Mid lengths leave offcuts and are less in demand. Price did not follow scarcity either: in the upswing, timber in short supply sold at the rate set for a normal market.
People
The two cultures priced the same customers by different rules. Sales teams had little guidance on pricing strategy, on negotiating and managing contracts, or on when and how far to discount to clear stock. Override reports were produced, but often nobody read or acted on them, and nobody faced a consequence for writing an override.
Structures
The SAP system held hundreds of thousands of customer and SKU price combinations. They were meant to map to price architectures and product hierarchies, but they did not, because permanent price overrides had been entered for customer after customer at SKU level. Each was a hard-coded number that changed only when someone changed it by hand. After ten years of this, across many account managers and thousands of products and customers, a list price change no longer flowed through as a consistent price rise. Some customers were paying the same price for a product five years later, while inflation had moved costs up 15 to 20 per cent.
Prices also bore little relation to volume. Some customers paid less than larger customers for the same product, and price points in one channel undercut another. The clash came to a head between Bunnings and Mitre 10 on a structural flooring product. And a sawmill keeps producing to hold throughput and recover its fixed costs, so mid-range lengths of around 3 metres built up in stock, were not cleared by any rule, and were often written off: timber left out in the weather turns black.
Six priorities followed.
Rebuild the list price architecture.
Correct relativities between products, grades and lengths, so the price reflects what the customer values and a list price change reaches every customer.
Set discounts by customer spend.
Customers of like size pay like prices, and price points in one channel stop undercutting another.
Pay large accounts for share of wallet.
Rebates for accounts spending A$1m or more, paid for bringing more of their spend, and tested before they are offered.
Write how customers order into the contract.
Order timing and load size, so the account carries the cost of the way it buys.
Clear surplus stock by rule.
Tactical discounts set by stock against sales, not by whoever is negotiating.
Judge every override on what the account earns, and act on the report.
03What Pricing Insight did: one pricing structure, from list price to contract
Six parts, each built on the one before. The list price set the reference point, and every other part was built on it.
A new list price architecture with correct relativities.
Prices set on one structure by product, grade and length, with a premium on the lengths builders value most. Customer prices were built from the list, so a list price change reached the invoice.
Discount entitlements by customer.
Every customer placed by its annual spend, with an entitlement and price points that match it. Customers buying similar volumes paid similar prices, and channel prices no longer clashed.
Performance-based rebates for accounts spending A$1m or more.
Rebate programs that packaged the customer's total purchases, so it paid to place more of its spend with Carter Holt Harvey instead of spreading it across suppliers. Each was built in a return on rebate investment model.
Contract clauses on how customers order.
Customers ordered at the right times and in the right quantities, half trailers or full trailers, instead of small orders with a higher cost to serve. The contracts set out the value supplied and the terms that captured it.
A stock-to-sales discount calculator.
Weeks of stock cover for every SKU, every week, with a discount that stepped up as cover rose, offered only to selected customers who held market prices. Scarce prime lengths were not discounted.
Overrides judged on the revenue and gross margin of the whole account, not one transaction at a time.
The return on rebate investment model tested each rebate before it was offered. The test is the extra gross margin a rebate buys, divided by the extra rebate it costs, with the proposed target checked against the customer's estimated total spend. A target the customer would reach without changing how it buys fails the test, whatever it returns on paper.
The stock-to-sales discount calculator
A weekly calculation for every SKU. Framing timber runs to a large matrix: lengths from 2.4 to 6.0 metres; sections of 70 x 35, 70 x 45, 90 x 35 and 90 x 45; MGP10 and MGP12 grades; and treated or untreated timber in the Frameshore red and Frameshore blue ranges. Each combination is its own SKU, and each needed managing every week. The calculator gave the business and its sales managers the weeks of stock cover for each one: stock on hand divided by the average weekly rate of sale.
It worked the way an airline prices the seats on a flight. Where weeks of cover sat at target, there was no discount. As cover rose above target, a discount stepped in and deepened as cover grew, so price and volume were calibrated SKU by SKU rather than by whoever was negotiating that week.
The second version changed who received the discount. Instead of offering it to every customer, the business offered it only to selected customers who would take the lower price on mid-range lengths, bank it as margin and hold their own prices in the market. Surplus stock moved without dragging down market prices, valued customers earned extra margin, and less timber sat in the yard long enough to weather and be written off.
04What changed: margin rebuilt at a tactical and a strategic level
Margin came back at two levels. At the tactical level, list price changes reached customers again, prime lengths carried their premium, surplus mid lengths were cleared before they were written off, and customers ordered in loads that cost less to serve. At the strategic level, customers of like size paid like prices, the channel clash left the price structure, and the largest accounts were paid for placing more of their spend with Carter Holt Harvey.
The stock-to-sales calculator added three gains of its own. Market prices held, because clearance discounts went only to customers who banked them as margin rather than passing them on. Those customers earned extra margin on mid-range lengths. And the business carried less excess stock and wrote off less weathered timber, which lowered its cost of doing business.
The sales teams wrote fewer price overrides. With entitlements set by spend and overrides judged on the account, an override became an exception with a reason, not the normal way to close a sale.
Status: capability built, with margin gains recorded by the business. Metric: gross margin, at line and account level. The dollar value of the margin gains, the change in override volumes and the share of wallet won at rebate accounts are not disclosed. Figures 2, 4 and 6 are illustrative arithmetic and Figure 7 is a diagram of the method; none is a client result. Customer prices and agreement terms are not disclosed. Fees are not disclosed.
05The Pricing Periodic Table elements this work built
Twelve elements built, four identified. The Pricing Periodic Table maps 61 elements of pricing capability in nine domains across three pillars: Value, People and Structures. Most of this work sits in the Price Architecture and Customer Agreements domains.
49 Lp and 52 Rl: the new list price architecture and the premium on prime lengths. 51 Dt and 08 Sg: discount entitlements by spend, and channel prices that no longer clash. 16 Rb and 39 Ka: performance-based rebates for accounts spending A$1m or more. 15 Va and 45 Pr: contracts that set out the value supplied and the order times and load sizes customers commit to. 46 Pm, Price modelling and 54 Co, Price corridors and exceptions: the stock-to-sales discount calculator, with clearance discounts offered only to customers who hold market prices. 44 Or and 24 Mc: overrides judged on account revenue and gross margin. The outlined elements are the next gains: a pricing playbook for the sales teams (31 Pb), a price increase process (43 Pi), clean SAP price records (57 Dq) and approval limits on overrides (61 Da).
06Three lessons for a CEO
A price keyed into the system is a decision that never ends
At Carter Holt Harvey Wood Products, some customers paid the same price five years later while costs had risen 15 to 20 per cent. Build customer prices from the list, so a list price change reaches the invoice, and give every exception an owner and an end date.
Price what the customer values and the stock you hold
A 6 metre length priced at the mid-length rate gives away the value builders place on it, and a surplus mid length with no clearance rule weathers in the yard and is written off. Relativities set the premium; a stock-to-sales calculator sets the clearance by weeks of cover, and offering it only to customers who hold market prices keeps the market price intact.
Pay large customers for share of wallet, and judge overrides on the account
A rebate for an account spending A$1m or more should buy more of its spend, and the return on rebate investment model shows whether it does before it is offered. An override judged on the account's revenue and gross margin has to earn its place.
07Questions this case study answers
How does a timber or building products manufacturer stop price overrides eroding margin?
Start by building every customer price from the list price, so that a list price change reaches the invoice, and remove the permanent overrides that freeze prices at customer and SKU level. At Carter Holt Harvey Wood Products, some customers paid the same price five years later while costs rose 15 to 20 per cent. Pricing Insight replaced them with a list price architecture and discount entitlements by spend, and judged overrides on the whole account.
How should a building materials supplier structure rebates for its largest trade and retail accounts?
Pay the rebate for a change in how the customer buys, usually more of its total spend, and test it before it is offered. At Carter Holt Harvey Wood Products, performance-based rebates were reserved for accounts spending A$1m or more and packaged their total purchases across timber and panels, so it paid to place more spend with one supplier.
How should a sawmill price timber lengths and surplus stock through the housing cycle?
Price each length on what builders value: the lengths that cut to standard wall heights with little waste carry a premium, and mid lengths a base rate. Set tactical discounts for surplus stock by rule, from weeks of stock cover for each SKU, the way an airline prices seats, and offer them only to customers who will bank the margin and hold their market prices. Carter Holt Harvey Wood Products had sold every length at one rate per metre; a new list price architecture and a stock-to-sales discount calculator moved surplus stock, held market prices and cut write-offs.
Related case studies · Building materials
How many of your customer prices still move when your list price moves?
A first conversation covers your price file, your largest rebate agreements and where overrides sit, and whether a diagnostic is warranted. Ron Wood, +61 410 534 099.
Ron Wood is the Founder and Managing Director of Pricing Insight, an Australian pricing strategy consultancy he established in 2007. He has worked in pricing for around 30 years, first as a pricing and commercial manager in consumer goods, building materials and capital equipment, and since then across 160+ pricing engagements. He also founded Pricing University, which has trained more than 5,000 executives.
To discuss your price architecture, rebates or contracts, contact Ron Wood at info@pricinginsight.com.au or on +61 410 534 099, or visit Pricing Insight.
Engagement details are from Pricing Insight's records of the work for Carter Holt Harvey Wood Products Australia. Company facts: the New Zealand Herald, on Carter Holt Harvey's purchase of CSR's particleboard and MDF business; the Australian Business Register, entry for Carter Holt Harvey Wood Products Australia Pty Limited (ABN 93 002 993 106), including the business name CHH Pinepanels. Carter Holt Harvey today trades in New Zealand as CHH Timber, CHH Ply, Futurebuild LVL and Carters (chh.com, reviewed 11 November 2026). The margin gains are as recorded from the engagement and are not disclosed or independently audited. Figures 2, 4 and 6 are illustrative arithmetic; Figure 6 is a Pricing University worked example; Figure 7 is a diagram of the method, and its band names and thresholds are not Carter Holt Harvey figures. No figure on this page is typical or guaranteed. Fees are not disclosed.


